i.
Licensed Realtor
Full-service representation for buyers and sellers across the Northwest suburbs, sharp pricing, steady negotiation, start to close.
If you’re facing foreclosure, doing nothing is the most expensive choice. As a foreclosure and short sale realtor, I’ll show you the paths still open, and time is the one thing that matters most.
Name, email, and phone, that’s all it takes. I’ll follow up personally to set up your consult.
Book a Free ConsultConfidential & no pressure.In Illinois you can sell your home any time before the court confirms the Sheriff sale, often right up to the auction. If you have equity, a normal sale lets you pay off the mortgage, stop the foreclosure, protect your credit, and keep what is left. If you owe more than the home is worth, a lender-approved short sale can do the same with far less credit damage than a completed foreclosure. As a foreclosure real estate agent, former appraiser, and licensed home inspector serving Mount Prospect and the Northwest suburbs, I will tell you which path fits and move fast. The expensive mistake is waiting.
Full-service representation for buyers and sellers across the Northwest suburbs, sharp pricing, steady negotiation, start to close.
I read a house the way an inspector does, structure, systems, and the costly surprises, before they cost you at the table.
A professional background in residential appraisal means I price and defend value from real data, not guesswork.
Falling behind on a mortgage is stressful and isolating, but it’s more common, and more solvable, than most people realize. Whether you have equity and can sell before foreclosure, or you owe more than the home is worth and need a short sale, the right move depends on your numbers. My job is to give you those numbers honestly and fast.
No judgment, no lectures, and no false promises that everything will be fine if it won’t. I won’t waste the time you don’t have.
A clear read on your equity and timeline, straight talk on short sale vs. selling outright, and experienced negotiation with your lender through closing.
A fast, honest read on value and equity using my inspector and former-appraiser background.
We identify exactly how much time you have before the situation forces a decision.
Sell now, short sale, or another route, we pick what protects you most.
I handle buyers and, when needed, the lender approval that a short sale requires.
People often treat “short sale” and “foreclosure” as the same bad outcome. They’re not, and the difference between them can shape your finances for years. Here’s the honest version.
A foreclosure is one of the most damaging marks a credit report can carry and it lingers. A short sale still hurts, but it typically does less long-term damage and, in many cases, lets you qualify for a new mortgage sooner. Selling before foreclosure, when you have equity, protects your credit most of all, because it closes as a normal sale.
Illinois allows lenders to pursue a deficiency judgment in a judicial foreclosure: the gap between what you owed and what the home brought. In a properly negotiated short sale, that deficiency can often be waived as part of the lender’s approval. That single term is one of the biggest reasons a short sale can beat letting the home go to auction, and it’s something I negotiate for directly.
When a lender forgives part of what you owe, the IRS can treat that forgiven amount as income in some situations. There are important exclusions, and it’s a conversation for a tax professional, but you should know the question exists before you sign, not after. I’ll flag it early so you can get the right advice.
Because a short sale is generally less severe than a foreclosure, the waiting period to qualify for a new home loan is often shorter. If getting back into a home down the road matters to you, that gap alone can make the short sale worth the effort.
I’m a Realtor, not an attorney or tax advisor, this is general information, not legal or tax advice. I’ll help you get the right professionals in your corner before any decision.
The right move depends entirely on where you stand, and most homeowners are not sure. Before you guess, I can tell you what your home is actually worth today, because I spent years as a residential appraiser and I am a licensed home inspector. Then the path is clear:
Your home is worth more than you owe. A normal, well-priced sale pays off the loan, stops the foreclosure, and puts the difference in your pocket. No short sale, and no deficiency to worry about.
The home is worth about what you owe. We sell it as-is and fast so you net close to zero and walk away clean, ahead of the court process.
This is where a lender-approved short sale comes in. I negotiate the sale with your lender and, as a condition of approval, work to have the shortfall waived so the debt does not follow you.
That is normal, and it is exactly what a first conversation is for. One honest valuation tells you which bucket you are in and what your real options are.
Illinois is a judicial-foreclosure state, so the process runs through the courts and gives you more time and more exit points than most people realize. Here is the sequence and where you can still act:
A signed contract before the Sheriff sale can stop the process. Cook County cases often move slower than DuPage or Lake, so we time everything to your specific court date.
Usually, yes. There are two speeds, and I time either one backward from your court date. A well-priced listing can reach a signed contract in a couple of weeks in this market. If the clock is tight, we sell as-is and fast. This is where my inspector background earns its keep: in one visit I can tell you what a buyer inspector will flag, so we price it right and do not lose weeks to inspection surprises that blow up a fast timeline.
I work with homeowners facing foreclosure throughout the Northwest suburbs: Mount Prospect, Arlington Heights, Des Plaines, Palatine, Park Ridge, Elk Grove Village, Rolling Meadows, and Wheeling. A foreclosure notice is a crisis, not a character flaw, and there is no judgment here, only a plan. Because Cook and Lake County courts move at different speeds, knowing the local pace keeps your sale on a realistic timeline.
In a foreclosure, the lender forces the sale of your home to recover the loan, you lose control of the process and the credit damage is severe. A short sale is a sale you arrange, with the lender agreeing to accept less than the full balance owed. It keeps you in the driver’s seat and usually does less long-term harm.
If your home is worth more than you owe, you may not need a short sale at all. Selling on the open market before the foreclosure completes can pay off the loan, protect your credit, and put the leftover equity in your pocket. The first thing I’ll do is give you a fast, honest read on value and your equity so you know which path you’re actually on.
Generally no. Both affect your credit, but a foreclosure tends to hit harder and stay longer, while a short sale often does less damage and can let you qualify for a new mortgage sooner. Selling before foreclosure when you have equity is the gentlest option of all because it closes as an ordinary sale.
In an Illinois judicial foreclosure the lender can seek a deficiency judgment for the gap between what you owed and what the home sold for. In a negotiated short sale, that deficiency can often be waived as a condition of approval, which is exactly the kind of term I work to secure for you.
Sometimes. The IRS can treat forgiven mortgage debt as taxable income, though several exclusions may apply. It’s a question for a tax professional, and I’ll make sure it’s on your radar before you sign anything rather than as a surprise the next year.
Illinois is a judicial-foreclosure state, so the process runs through the courts and typically takes many months from the first missed payments to an auction, but that clock is not on your side. The earlier we act, the more options stay open, which is why the very first step is mapping exactly how much time you have.
In most short sales the lender’s payoff covers the standard sale costs, including the agent commission, so sellers usually pay little to nothing out of pocket. I’ll give you a clear picture of your specific numbers up front, no surprises.
It varies by loan type and your overall credit, but the waiting period after a short sale is generally shorter than after a foreclosure. If buying again is a goal, that shorter path back is one more reason a short sale often beats letting the home go to auction.
Yes. You can sell any time before the court confirms the Sheriff sale, which in practice can be right up to the auction. A signed contract before that point can stop the process entirely. The sooner you start, the more options and time you have.
Reinstating means bringing the loan current by paying the missed payments and fees during the roughly 90-day reinstatement window, and the loan simply continues. Redeeming means paying the entire remaining balance to keep the home, available during the redemption period of about 7 months from service or 3 months from judgment. Selling is often the practical middle path when neither is realistic.
No. If your home is worth more than you owe, it is a normal sale. You pay off the mortgage, the foreclosure stops, and you keep the difference. A short sale only comes into play when you owe more than the home is worth.
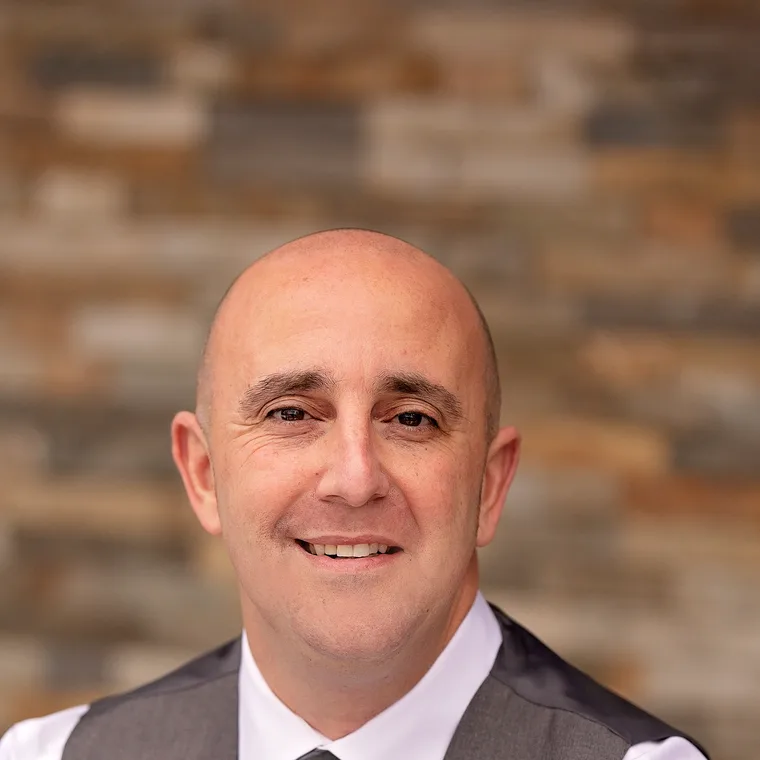
I’m a licensed REALTOR® and licensed home inspector with a professional background in residential real estate appraisal, a combination that sets me apart from more than 50,000 agents across Illinois and lets me guide you at a deeper level through every buying or selling decision.
Whether you’re selling an inherited home, staying ahead of a foreclosure, downsizing, or buying your next place, you get one advisor who understands construction, condition, and true value.
Before real estate, I spent years as a firefighter and paramedic. Showing up calm when someone is having the worst day of their life is what I did for a living. A foreclosure is a crisis, not a character flaw, and it has a plan we will work one step at a time.
Related reading: How to Sell an Inherited House in Illinois, including what to do when the home you inherited still has a mortgage on it and the payments have fallen behind.