i.
Licensed Realtor
Full-service representation for buyers and sellers across the Northwest suburbs, sharp pricing, steady negotiation, start to close.
Downsizing a longtime home is as emotional as it is logistical. I bring a patient, organized plan for the sale and the move, and an honest read on what decades in one home are really worth today.
Name, email, and phone, that’s all it takes. I’ll follow up personally to set up your consult.
Book a Free ConsultConfidential & no pressure.The best way to help a longtime homeowner downsize is to work with an agent who can tell you honestly what the home is worth as-is versus after repairs, time the sale so you are never without a place to live, and coordinate the movers, the downsizing help, and your CPA, so one person quarterbacks the whole transition. As a Realtor who is also a former appraiser and a licensed home inspector, and who has spent years helping families across Mount Prospect and the Northwest suburbs make this exact move, I read a dated home the way a buyer inspector will and price it so you never leave money on the table. That is the difference between a stressful scramble and a calm, planned move.
Full-service representation for buyers and sellers across the Northwest suburbs, sharp pricing, steady negotiation, start to close.
I read a house the way an inspector does, structure, systems, and the costly surprises, before they cost you at the table.
A professional background in residential appraisal means I price and defend value from real data, not guesswork.
The home you raised a family in carries more than furniture. Selling it deserves an advisor who moves at your pace, coordinates the moving parts, and gives you the full financial picture before any decision is made. With a background in home inspection and appraisal, I can tell you what the house needs, what it’s worth, and which improvements are worth making at this stage, and which aren’t.
No rushing, and no pressure to pour money into a home you’re about to leave. Your comfort and your equity come first.
Patience, a clear plan for the home and the move, and a trusted point of contact for the whole family through closing.
Downsizing isn’t one decision, it’s a dozen happening at once: what to keep, what to sell, where to land, and how to pay for it. You shouldn’t have to project-manage all of that alone. I bring a calm plan and the right people so the pieces happen in the right order.
The house is full of a lifetime, and that’s often the hardest part. I connect you with trusted estate-sale professionals, donation services, and cleanout crews, and we sequence it so the home shows well without you having to empty it in a weekend. Keepsakes stay with family; the rest is handled with dignity, not a dumpster rush.
The biggest worry I hear is “What if I sell and have nowhere to go, or buy and get stuck with two payments?” We build the timeline backward from where you’re headed, a smaller home, a condo, an active-adult or senior community, or a family member’s place, and coordinate the sale so the two line up. Where a rent-back or flexible closing helps, I negotiate for it.
Before any of it, you get an honest, appraiser-informed read on what the home is worth today and what your equity really is. That number drives everything that follows, what you can afford next, and whether any pre-sale work is even worth doing. If most of the mortgage is paid off, we’ll talk through the options that opens up.
Vito is completing the Seniors Real Estate Specialist (SRES®) coursework to deepen his focus on downsizing and senior moves.
A home lived in for decades is usually where the biggest, most emotional decisions get made, and the easiest place to waste money. This is my strongest lane. In an earlier chapter of my career I worked as a licensed residential appraiser, and I am a currently licensed home inspector, so I walk your home the way a buyer inspector will: the 40-year-old furnace, the original electrical panel, the roof age, the kitchen and baths.
Then I tell you which fixes actually return more than they cost and which ones to skip and price around. Most longtime owners over-improve a home they are leaving. You do not have to.
Deep clean and declutter, minor paint, obvious safety items, and anything a buyer inspector will flag and use to renegotiate.
Full kitchen or bath remodels, new flooring throughout, and big-ticket updates a buyer would redo to their own taste anyway. Price the home as-is instead.
Every repair on a dated home has to pass one test: does it change what a buyer offers, or keep a buyer from walking away? On a home you have owned for decades, most big projects fail that test. Because I inspect homes for a living, the list I give you is the same list the buyer’s inspector will produce, so nothing on it surprises us mid-contract.
The skip list is where longtime owners lose real money, spending tens of thousands to make the home theirs one more time instead of ready for the next family. If the better answer for your situation is selling as-is at an honest price, I will tell you that plainly, with the numbers to back it up.
The hard part of downsizing is rarely the listing. It is the decades of belongings and the logistics. I quarterback the pieces so your family is not doing it alone: senior move managers, many of whom belong to the National Association of Senior and Specialty Move Managers, estate-sale professionals, and cleanout crews. I sequence the handoffs so the sale, the sort-through, and the move to the next place all line up instead of colliding.
No one should be homeless in the middle of a move. Depending on whether you are heading to a condo, an active-adult community, or assisted living, we plan the order deliberately. Sometimes that means selling first and negotiating a rent-back so you stay in the home for a set period after closing. Sometimes it means lining the closing up with a move-in date. Either way, the plan comes before the for-sale sign.
If you bought decades ago, your home has likely gained a lot of value, which is wonderful and raises a fair question about taxes. In plain terms, a married couple can generally exclude up to 500,000 dollars of gain on a primary residence, and a single owner up to 250,000 dollars, under the federal home-sale exclusion. Decades of home-improvement receipts can also raise your cost basis and reduce the taxable gain, which is why they are worth digging up.
I am not a tax advisor, but I flag this early and coordinate with your CPA so nothing is a surprise at closing. Most families we help across Mount Prospect, Arlington Heights, Des Plaines, Palatine, Park Ridge, Elk Grove Village, Rolling Meadows, and Wheeling owe far less than they feared, once the numbers are actually run.
The rule behind those numbers is Section 121 of the federal tax code, the primary-residence capital gains exclusion. A single owner can generally exclude up to 250,000 dollars of gain from the sale of their main home, and a married couple filing jointly up to 500,000 dollars. The key word is gain: what is measured is not the sale price, but the difference between what you sell for and your cost basis, meaning what you paid plus documented improvements over the years.
To qualify, you generally must have owned the home and lived in it as your main home for at least two of the five years before the sale. The two years do not have to be consecutive. For someone who has lived in the same house for decades, that test is usually easy to pass.
A worked example, for illustration only. Say you bought your home for 120,000 dollars years ago and sell it today for 520,000 dollars. The gain is 400,000 dollars. A married couple filing jointly could generally exclude all of it, meaning no federal capital gains tax on the sale in that example. A single owner could exclude 250,000 dollars, leaving tax due only on the remainder, and even that shrinks once improvement receipts raise the basis.
One important boundary: the exclusion applies to a primary residence, not to a rental or an inherited or probate home, which follows different rules that are often even more favorable. I am not a tax advisor, so your CPA confirms how the rules apply to you, but I make sure the question is asked before you list, not after you close.
If you are downsizing and settling a parent’s estate at the same time, and the estate home is in Arlington Heights, the Arlington Heights probate real estate agent page lays out the estate side step by step so the two sales do not collide.
There’s no single answer, but the honest signals are usually the same: the home has more space, stairs, or upkeep than you use, and maintaining it is starting to cost more energy than it gives back. The best time is before a health event or a rushed deadline forces it, when you can move at your own pace and on your own terms. A no-pressure conversation is a good place to start weighing it.
You don’t handle it alone. I coordinate estate-sale specialists, donation pickups, and professional cleanout crews, and we sequence everything so the home is ready to show without you having to empty it overnight. Family keepsakes are set aside first; everything else is handled respectfully.
It depends on your finances and your comfort with moving twice, and it’s the question that causes the most worry. We map it out together and build the timeline so you’re never stuck with two payments or nowhere to go. When it helps, I negotiate a flexible closing or a rent-back so you can sell and settle without being rushed.
Almost never a full renovation. It’s easy to pour money into a home you’re leaving and never see it back. Because I read condition as an inspector and value as a former appraiser, I’ll tell you the short list of things that actually pay off, often just a deep clean, minor fixes, and light staging, and what to skip.
That’s welcome and common. I’m happy to keep the whole family looped in with the same clear information, so decisions get made together instead of through second-hand worry. One patient point of contact for everyone takes a lot of the friction out.
A lot of good ones. Strong equity gives you flexibility, buying the next place outright, keeping cash for retirement or care, or a mix. I’ll give you the honest value picture and, where it makes sense, point you to the right financial professionals so the move supports the next chapter, not just ends this one.
Often far less than people fear. A married couple can generally exclude up to 500,000 dollars of gain on a primary residence, and a single owner up to 250,000 dollars, under the federal home-sale exclusion. Old improvement receipts can raise your cost basis and lower the taxable gain. I am not a tax advisor, so confirm the details with your CPA, and I will coordinate so nothing is a surprise at closing.
Usually a light touch, not a remodel. As a former appraiser and a licensed home inspector, I walk the home the way a buyer inspector will and tell you which fixes return more than they cost and which to skip. Most longtime owners over-improve a home they are leaving. As-is, priced right, is often the smarter move.
You do not do it alone. I coordinate senior move managers, estate-sale professionals, and cleanout crews, and I sequence the handoffs so the sort-through, the sale, and the move all line up instead of colliding.
Then we move calmly and fast. We can sell as-is, and I will time the closing and options like a rent-back so you are never without a place to live. A paramedic career taught me how to move quickly without rushing the people who matter.
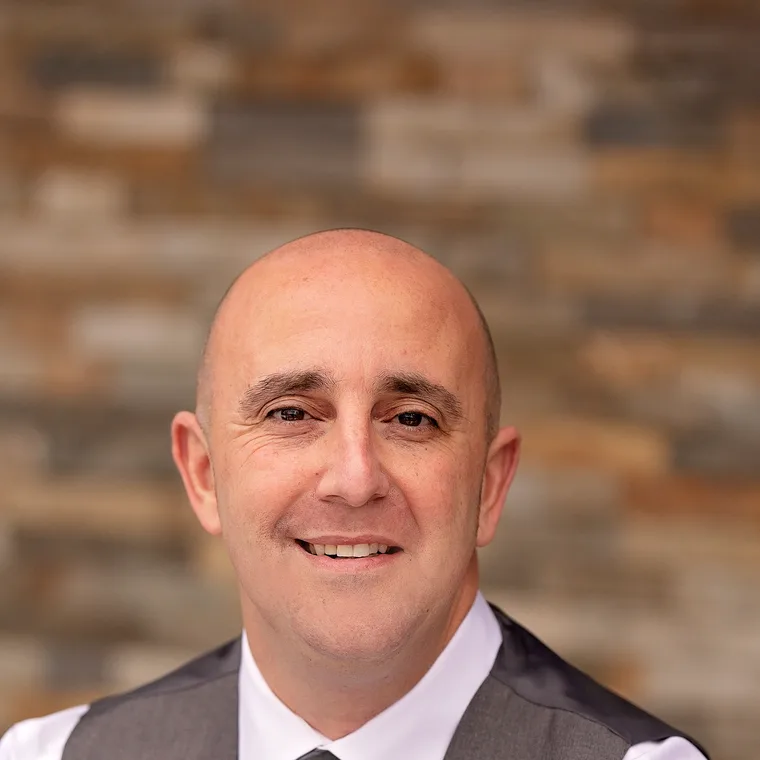
I’m a licensed REALTOR® and licensed home inspector with a professional background in residential real estate appraisal, a combination that sets me apart from more than 50,000 agents across Illinois and lets me guide you at a deeper level through every buying or selling decision.
Whether you’re selling an inherited home, staying ahead of a foreclosure, downsizing, or buying your next place, you get one advisor who understands construction, condition, and true value.
Before real estate, I spent a career as a firefighter and paramedic. Staying patient when the stakes are high is second nature, and a family leaving a home they have loved for 40 years deserves exactly that.
Related reading: How to Sell an Inherited House in Illinois, many downsizing families are also settling an estate, here is how the two processes fit together.
When the move follows a death rather than a decision, the sort-through runs on different rules. I wrote out how to clean out a house after a death, including what an executor may sell before the court issues letters and which donation receipts the IRS will accept.